

RDSP Withdrawals Explained: Avoiding Costly Surprises
Opening a Registered Disability Savings Plan (RDSP) is one of the best ways to secure the long-term financial future of a loved one with a disability. These accounts can grow with government grants and bonds, making them a powerful tool. But here’s where many families get caught off guard: understanding how withdrawals work.
Pulling money out of an RDSP isn’t as simple as taking out cash from a bank account. The type, timing, and source of the money all affect how much you actually keep — and whether government contributions are lost along the way. Let’s look at the rules, examples, and strategies to help you avoid costly surprises.
Who Can Make Withdrawals
Withdrawals from an RDSP must be made by the plan holder, the person responsible for managing the account on behalf of the beneficiary. The plan holder can be a parent, guardian, legal representative, or in some cases, the beneficiary themselves. Whoever holds the role must act in the best interest of the beneficiary.
Types of Withdrawals
There are two main ways to take money out of an RDSP:
Disability Assistance Payments (DAPs): One-time withdrawals that can be requested as needed. Families often use them for large expenses such as medical equipment, accessibility renovations, or specialized care. Before age 60, DAPs are subject to the 10-year repayment rule, but after age 60, that rule no longer applies.
Lifetime Disability Assistance Payments (LDAPs): Annual withdrawals that must begin no later than the year the beneficiary turns 60. Once they start, they continue every year for life. The government sets both minimum and maximum withdrawal amounts.
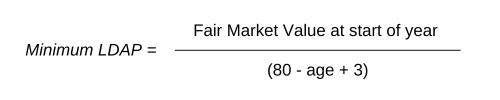
Minimum LDAP payments:
-
If LDAPs start before age 60, the minimum can be as little as $1 per year.
-
Once the beneficiary turns 60, the minimum is set by a formula. (This ensures the account provides income throughout the beneficiary’s lifetime.)

The 10-Year Proportional Repayment Rule
One of the most misunderstood RDSP features is the “holdback” or repayment rule. It protects government contributions by requiring repayment if withdrawals are made too soon.
For every $1 withdrawn, up to $3 of grants and bonds deposited in the last 10 years may have to be repaid.
Example of what can go wrong:
The Lee family opened an RDSP for their son Daniel. At age 30, they withdrew $5,000 for a wheelchair. Because $20,000 in government contributions had been deposited within the last 10 years, they had to repay $15,000. The repayment applied only to grants and bonds received in the last 10 years, not the lifetime total.
Example of planning done right:
The Martins waited until more than 10 years had passed since the last government contribution before withdrawing $10,000 for their daughter Emily. As a result, no grants or bonds had to be repaid. Emily kept every dollar of government support while also enjoying a tax-friendly income stream.
Important note: After the beneficiary turns 60, the 10-year repayment rule no longer applies.
Taxes and Benefit Impacts
Withdrawals are made up of two parts:
-
Taxable amounts — government grants, bonds, and investment growth.
-
Non-taxable amounts — original contributions, which can be withdrawn tax-free.
Financial institutions may withhold tax at the source. However, depending on the beneficiary’s overall income, some or all of that tax may be refunded at tax filing time. Using CRA’s tax tools or working with a qualified advisor can help you estimate the true impact.
Most federal programs do not treat RDSP withdrawals as income when determining benefits. But provincial and territorial programs vary. In some provinces, withdrawals may affect eligibility for certain disability or income supports. It’s always important to check local rules before making withdrawals.
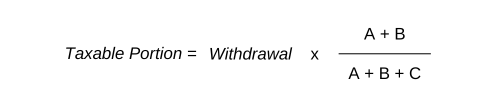
Quick Reference: Formula for Taxable vs. Non-Taxable Portions
Where:
-
A = total Canada Disability Savings Grants (CDSGs) in the plan
-
B = total Canada Disability Savings Bonds (CDSBs) + investment growth
-
C = total personal contributions
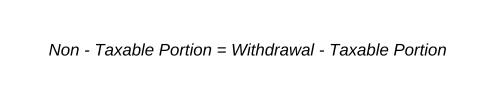
Example: If the RDSP holds $40,000 in grants and bonds (A + B) and $20,000 in contributions (C), then:
-
66.7% of each withdrawal is taxable
-
33.3% is non-taxable
So if you withdraw $3,000:
-
Taxable portion = $2,000
-
Non-taxable portion = $1,000
This ensures contributions are always tax-free, while government funds and growth are taxed.
Shortened Life Expectancy Withdrawals
In situations where a medical doctor certifies that the beneficiary’s life expectancy is five years or less, special rules apply. These allow the plan holder to withdraw more money than normal, regardless of standard annual limits.
-
Greater flexibility: The usual maximum withdrawal limits for LDAPs no longer apply. Families can access funds faster to cover increased medical or personal care costs.
-
10-year rule still applies: If government contributions were received in the last 10 years, some repayment may still be required.
-
Taxable split remains: Withdrawals are still divided into taxable and non-taxable portions using the CRA formula.
This provision ensures that beneficiaries with shortened life expectancy can benefit from their savings when they need them most, rather than being restricted by long-term withdrawal schedules.
Special Considerations
-
Hardship Withdrawals: In rare cases of severe financial need, exceptions can be requested to withdraw more than the standard limits. These must be approved, and rules differ by institution.
-
Institutional Rules and Fees: Not all banks allow early withdrawals, and some may charge fees. Always check with your RDSP provider about their policies before requesting a withdrawal.
-
Timing and Growth: Withdrawing too early not only risks repayment of government contributions but also reduces the long-term growth potential of the account.
Strategies to Minimize Clawbacks and Taxes
-
Delay withdrawals until at least 10 years after the last grant or bond.
-
Coordinate withdrawals with lower-income years for the beneficiary.
-
Use smaller, planned withdrawals instead of large lump sums.
-
Review LDAP rules well before age 60 to plan around the minimum and maximum requirements.
-
Be aware of shortened life expectancy rules if relevant, to ensure funds are used when most needed.
Common Mistakes to Avoid
-
Withdrawing too early and triggering grant/bond repayments.
-
Overlooking taxes and assuming withheld amounts are final.
-
Not checking provincial rules and losing other benefits.
-
Ignoring institutional rules or fees that affect access.
-
Closing the account too soon, which may forfeit contributions and growth.
The RDSP is a powerful way to build financial security for someone living with a disability. But withdrawals need careful planning. By understanding the repayment rules, tax impacts, and provincial variations, families can avoid costly mistakes and make the most of government support.
If you have an RDSP, it’s worth reviewing your withdrawal strategy early — well before you need to access the funds. A clear approach can help ensure your loved one benefits fully from this valuable program.
If you’d like guidance on creating a withdrawal strategy that fits your situation, consider reaching out to an advisor who understands RDSP rules and disability benefits. Careful planning today can help secure peace of mind for tomorrow.
Sources:
Canada Revenue Agency. Registered Disability Savings Plan (RDSP). Government of Canada, 2024, www.canada.ca/en/revenue-agency/services/tax/individuals/topics/registered-disability-savings-plan-rdsp.html
Employment and Social Development Canada. RDSP Withdrawals. Government of Canada, 2024, www.canada.ca/en/employment-social-development/programs/disability/savings/withdrawals.html
Canada Revenue Agency. What Types of Payments Can Be Made from an RDSP. Government of Canada, 2024, www.canada.ca/en/revenue-agency/services/tax/individuals/topics/registered-disability-savings-plan-rdsp/payments-rules/what-types-payments-made-rdsp.html
The LDAP formula assumes that the beneficiary will live until he turns 80 years. Certain disabilities, like Down syndrome, have an average life expectancy of 60 years. They die from typical aging issues, 20 years ahead of the rest of us. A medical practitioner will not certify that they are unlikely to survive for an additional five years. Is the RDSP effective for them?